Firmus IPO collapse shows Nvidia’s AI bottleneck is shifting from chips to capital
Bloomberg News / Bloomberg Tax
news
Nvidia-Backed Firmus IPO Being Pulled Sends AI Funding Warning
Bloomberg News / Bloomberg Law
news
Nvidia-Backed Firmus IPO Collapses as AI Valuation Concerns Grow
Bloomberg News / Bloomberg Tax
news
Data Center Darling’s $30 Billion IPO Dream Crushed in 48 Hours
IPO pulled
Firmus abandoned a planned roughly $5 billion Australian listing after weak investor demand and valuation pushback.
AI scrutiny
Investors questioned whether AI data-center growth assumptions justified the company’s proposed valuation and leverage.
Power risk
The failed float highlighted investor concern over the power, debt and utilization requirements behind AI infrastructure.
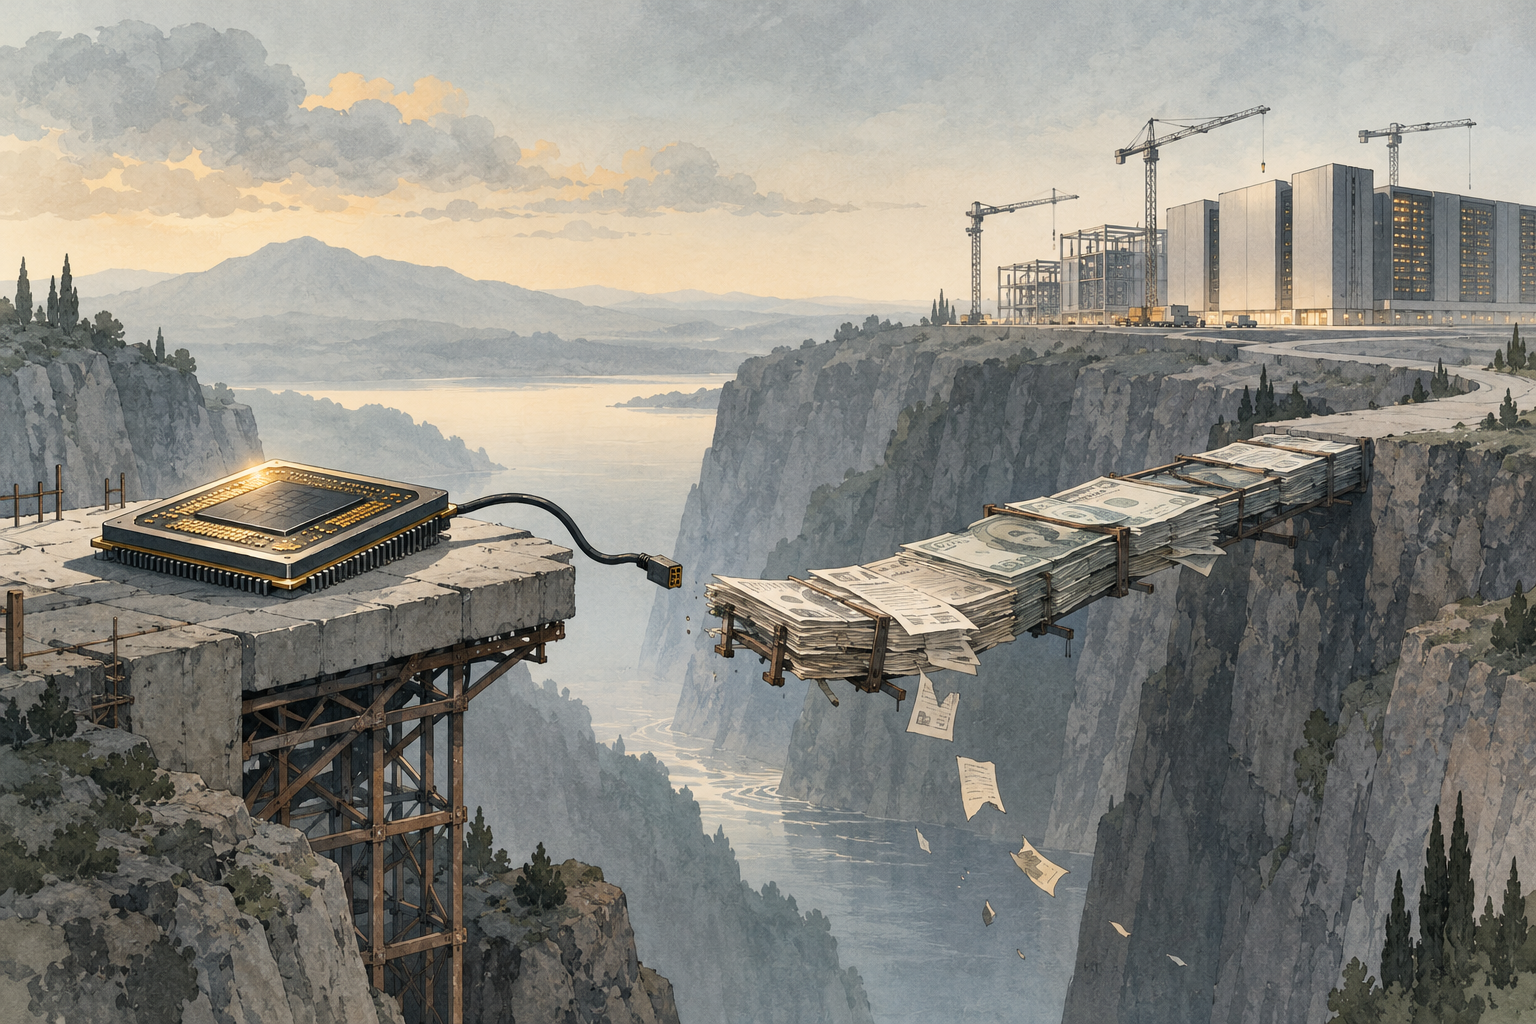
Firmus Grid’s failed attempt to list in Australia is more than a local IPO embarrassment. It is a stress test for the financing model behind the AI infrastructure boom — and a warning to Nvidia investors that the next bottleneck may not be demand for graphics processing units, but the market’s willingness to fund the data centers meant to absorb them.
The Nvidia-backed Australian data-center company scrapped a planned roughly $5 billion listing after investors pushed back on valuation, leverage, limited operating history and the assumptions embedded in its AI growth story.25 Bloomberg reported that weak support for the A$11 marketed price forced the company to withdraw the offer, framing the collapse as an early warning on AI infrastructure funding.1 Reuters and Australian media similarly cited lacklustre demand, debt concerns and questions about execution as central reasons the blockbuster float was pulled.510
That matters because Nvidia’s AI demand story increasingly depends on a vast second-order capital cycle. Hyperscalers, neocloud operators, utilities, landowners, power-equipment suppliers and lenders all must fund infrastructure before Nvidia’s accelerators can be installed, powered and monetized. Firmus suggests public markets are asking a harder question: not whether AI compute will be needed, but who will finance it, on what terms and with what evidence of utilization.
The immediate facts are clear. Firmus, a data-center operator tied to the AI buildout, tried to complete one of Australia’s largest listings in years, but the bookbuild deteriorated quickly. Bloomberg said the deal was abandoned after investors resisted the proposed valuation, while a follow-up account described how the company’s ambitious market debut unraveled in days.23 Reuters reported that the company had nearly tripled in valuation since August, a pace that appears to have amplified, rather than eased, investor skepticism.5
The reversal followed signs of strain even before the formal cancellation. ABC News reported that investor interest was underwhelming and that the company was considering a repricing from A$11 to roughly A$8 to salvage the listing.11 Reuters Breakingviews likewise described Firmus as scrambling to rescue the float after a price cut, calling the episode a sign that investors were no longer treating AI-linked infrastructure as automatically scarce — and therefore automatically financeable.7
By October 9, the float was off. Firmus withdrew its ASX listing application after what ABC characterized as poor investor interest, with concerns including debt levels and insufficient detail around the business.10 The Guardian reported that the company had pulled what would have been the largest ASX float since Telstra amid doubts about valuation and forecast earnings relative to its still-young operating footprint.13
For Nvidia, the key distinction is that Firmus did not fail because investors stopped believing in AI chips. It failed because equity investors balked at underwriting the physical and financial bridge between chip orders and durable cash flow.
The Firmus episode exposes a widening gap between private-market AI enthusiasm and public-market discipline. Data-center capacity is being valued as a scarce strategic asset, but public investors are starting to demand conventional proof: signed customers, power access, funding certainty, utilization history, credible debt capacity and visible margins.
Reuters Breakingviews put the issue bluntly, arguing that investors balked at paying up for a data-center operator with a limited track record.6 ABC’s post-mortem pointed to concerns about power infrastructure, valuation and broader anxiety over an AI bubble.12 Data Center Dynamics reported that the company canceled the IPO after weak demand and had already reduced the proposed share price, underscoring how quickly sentiment turned once institutional investors had to commit capital rather than simply admire the theme.15
The significance is not that one Australian issuer mispriced a deal. It is that Firmus sat at the intersection of several pressure points now relevant across the AI stack:
In other words, Nvidia’s chips may remain supply-constrained or demand-rich, but the infrastructure layer can still become capital-constrained.
The market reaction also clarifies the limits of strategic association. Nvidia backing can validate technical relevance, but it does not eliminate project-finance risk. Investors still have to decide whether a data-center company can build, connect, lease and operate capacity profitably enough to justify its valuation.
That distinction is critical for semiconductor investors. Nvidia has benefited from a powerful feedback loop: more AI models require more compute, more compute requires more accelerators, and more accelerator deployments encourage more data-center construction. But if data-center funding becomes more expensive or selective, that loop can slow even if end demand for AI remains strong.
Bloomberg reported that Firmus began exploring a private round of about $3 billion after shelving the IPO, suggesting the company may still raise capital outside public markets.4 But that would not erase the signal from the failed float. If anything, it suggests a bifurcation: private investors may still fund AI infrastructure, but public investors are demanding a discount, more evidence or both.
Private capital can delay price discovery, but it cannot repeal it. If public markets refuse to validate aggressive valuations, private rounds may become smaller, more structured, more expensive or more dependent on strategic investors. For infrastructure companies, that can mean a higher cost of capital. For chip suppliers, it can mean customers and partners become more sensitive to deployment timing, financing terms and utilization risk.
Firmus’s failed IPO was not contained to a single issuer. Reuters reported that shares of Maas Group, a Firmus investor, fell after the IPO was pulled, reflecting investor reassessment of stake valuation and exposure to related infrastructure contracts.9 Reuters also described the collapse as a blow to Australia’s shrinking share market, noting the scale of the aborted deal in the context of weak IPO conditions.8
That spillover is important. AI infrastructure is not just a semiconductor story; it is an ecosystem of listed and unlisted claims on the same growth assumptions. Construction firms, landowners, utilities, cooling providers, fiber networks, equipment suppliers, private credit funds and chip vendors can all benefit when data-center valuations rise. They can also all be repriced when investors question whether the buildout is being financed on realistic assumptions.
The Guardian’s timeline of the collapse highlighted concerns during the bookbuild, including early-holder sell-down risk and the final withdrawal.14 That detail matters because IPO buyers often dislike deals where existing holders appear eager to monetize a narrative before the business has matured. In AI infrastructure, the optics of insiders selling into public-market enthusiasm can sharpen concern that the valuation cycle has moved faster than operating proof.
For Nvidia investors, the Firmus collapse should not be read as evidence that accelerator demand is suddenly impaired. The stronger conclusion is narrower but still important: capital markets are becoming more discriminating about the infrastructure companies that convert AI demand into deployable compute.
The practical watch points are:
This is the financing version of a supply-chain bottleneck. In the first phase of the AI boom, investors focused on whether Nvidia could produce enough chips. In the next phase, they may focus on whether the ecosystem can fund enough powered, connected and utilized facilities to house them.
The most important lesson from Firmus is that AI infrastructure is becoming investable only where the underwriting is specific. Broad exposure to data centers, Nvidia relationships or AI demand is no longer enough. Public investors want proof that the economics work at the project level.
That does not end the AI infrastructure boom. It may make the boom healthier by forcing capital toward operators with real sites, real power, real customers and realistic leverage. But it also creates a risk for Nvidia’s ecosystem: if financing discipline tightens faster than compute demand grows, the constraint shifts from silicon availability to balance-sheet credibility.
Firmus’s abandoned float is therefore a warning flare, not a verdict. Nvidia may still sit at the center of the AI economy. But the market is starting to test whether the infrastructure around it can support valuations built on rapid growth, heavy borrowing and assumptions of near-frictionless demand. The answer will help determine whether AI capital spending remains a self-reinforcing cycle — or becomes a more selective, more expensive race for bankable capacity.

U.S. ocean container imports reached a September record, with China-origin shipments up 21.2%, underscoring resilient consumer demand and retailer restocking. The same surge complicates the macro picture by raising questions about inventory buildup, tariff timing and whether goods-price disinflation can keep helping inflation ahead of CPI.

France’s 2027 budget has not stopped investors from demanding a larger premium for holding OATs, raising the question of whether Paris is still priced as a core euro-area borrower. The repricing is feeding into the euro, narrowing the traditional gap between French and Italian debt risk, and complicating the European Central Bank’s room to keep tightening.

Thirty-year gilt yields near 6% are signaling that investors are charging the UK a credibility premium ahead of the 28 October Budget. A November Bank of England hike may support sterling, but it may not be enough to cap long-end yields if fiscal plans fail to reassure markets.

JPMorgan, Goldman Sachs, Citigroup and Wells Fargo report before the open on Tuesday, October 13, giving investors the first major read on whether rising Treasury yields are lifting bank income or starting to hurt loan demand, market activity and valuations.
Neocloud
A cloud or data-center operator focused on providing high-performance compute capacity, often for artificial intelligence workloads.
Bookbuild
The process in which investment banks gauge investor demand and pricing for an initial public offering before shares are listed.
Utilization risk
The risk that expensive data-center or compute capacity will not be leased or used enough to generate expected returns.
Cost of capital
The return investors and lenders demand to finance a company; a higher cost of capital makes expansion more expensive.
Comments