Finance
0 followers·170 articles
Premier Inn Growth Buys Whitbread Time, Not a Free Pass
October 14, 2026
Whitbread’s first-half results show Premier Inn still gaining accommodation revenue in the UK and Germany, but the investment case now depends on whether that growth can compound faster than cost inflation, impairments and activist pressure. Corvex’s board-seat campaign turns the hotel group into a live test of how much patience investors still have for UK consumer-sector self-help plans.
9m
5m
BP rally tests investor patience with low-carbon write-downs
BP’s third-quarter update put a sharp refining-margin uplift and faster deleveraging ahead of another multibillion-dollar impairment charge tied mainly to transition businesses. The share-price reaction suggests investors are prioritising near-term cash generation, but the reset leaves capital-discipline questions unresolved.
7m
ASML’s AI Boom Shifts the Debate to Bottleneck Risk
ASML’s record Q3 results validate the artificial-intelligence capital-spending cycle, but they also expose the next constraint: whether Europe’s most important semiconductor-equipment supplier can expand lithography capacity fast enough through 2028. For investors, the question is moving from whether AI demand is real to whether supply, export controls and order timing can sustain ASML’s valuation.
6m
China’s factory-gate rebound points to margin squeeze before inflation pass-through
China’s producer prices are rising at their fastest pace since mid-2022, but consumer inflation remains subdued. That mix suggests global supply chains may face higher input-cost pressure before importers and households see clear pass-through.
Bytes Technology’s AI growth story faces a margin test
October 13, 2026
Bytes Technology’s half-year update gives UK mid-cap investors a cleaner read on corporate software, cloud and cybersecurity demand, but the key question is whether growth is being converted into higher-quality profit. AI is becoming a more meaningful demand driver, while higher technology costs and normalised bonuses are keeping operating leverage under scrutiny.
7m
5m
Japan’s PPI Miss Is Not Enough to Let the BOJ Stand Down
Japan’s September corporate goods prices cooled more than expected, but yen-based import prices still surged 24.5%, keeping cost-push pressure alive. For global macro investors, the signal is less disinflation than a narrower path for the Bank of Japan ahead of its late-October policy meeting.
8m
Bellway’s FY27 outlook checks hopes for UK housebuilder rally
Bellway’s full-year results point to resilience in cash generation but not yet a clean demand recovery. Its FY27 guidance implies lower completions, further margin pressure and continued reliance on bulk sales while mortgage affordability and build-cost inflation remain the sector’s dominant constraints.
5m
LVMH’s Q3 slowdown challenges luxury’s China offset thesis
LVMH’s third-quarter sales showed that growth in the US, Europe and Japan is not yet enough to neutralize weaker Chinese demand in high-margin fashion and leather goods. The update makes the French group the first major test of whether European luxury can sustain a recovery without a stronger China consumer.
Hays’ fee slide puts Michael Page under scrutiny as hiring slowdown widens
October 13, 2026
Hays’ 14th consecutive quarterly net-fee decline suggests the UK and European hiring slowdown is showing up in listed recruiter revenues, not just official labour data. Michael Page’s next update will test whether the pressure is company-specific or sector-wide.
7m
7m
SpaceX Spectrum Deal Tests European Telecoms’ Defensive Case
A U.S. spectrum acquisition is being priced as more than an American wireless story: European telecom investors are reassessing whether mobile cash flows remain as durable as sector valuations and dividends imply. The immediate selloff may prove excessive, but the valuation debate has shifted from coverage novelty to competitive optionality.
9m
India’s Rupee Defense Turns Oil Shock Into EM Dollar-Liquidity Warning
The Reserve Bank of India’s decision to steer state oil companies’ dollar purchases away from the spot market is more than a rupee-support tactic. It shows how high oil prices, a strong dollar and capital outflows can push emerging-market central banks toward crisis-style balance-of-payments management.
7m
UK August GDP Puts the Growth Trade’s Credibility on Trial
The ONS will publish August GDP and the main activity breakdowns at 7:00am on 15 October, giving investors a cleaner test of whether UK growth is still being led by broad services momentum or flattered by revisions. Sterling, domestically exposed equities and Bank of England pricing are likely to react less to the headline than to the mix beneath it.
UK card defaults expose early strain on household balance sheets
October 12, 2026
The Bank of England’s Q3 Credit Conditions Survey shows unsecured credit stress rising even before headline spending has fully weakened. That points to a consumer sector absorbing higher rates and living costs through deteriorating household balance sheets, with implications for banks, retailers and the Bank of England’s policy trade-off.
8m
6m
Airtel Money gives London a rare fintech win, but not yet an IPO-market turnround
Airtel Money’s London debut is a sizeable boost for the Main Market, but its secondary-sale structure, discounted valuation and muted early trading make it a narrow test of investor appetite rather than proof of a broader issuance revival.
8m
Firmus IPO collapse shows Nvidia’s AI bottleneck is shifting from chips to capital
Firmus Grid’s abandoned roughly $5 billion float is a warning that public investors are no longer willing to underwrite every AI infrastructure story at venture-style valuations. For Nvidia and its ecosystem, the harder constraint may increasingly be the credibility and cost of funding the data-center buildout that keeps chip demand compounding.
5m
Record September Imports Bolster Growth Signal — and Revive Inflation Questions
U.S. ocean container imports reached a September record, with China-origin shipments up 21.2%, underscoring resilient consumer demand and retailer restocking. The same surge complicates the macro picture by raising questions about inventory buildup, tariff timing and whether goods-price disinflation can keep helping inflation ahead of CPI.
France’s Budget Stress Blurs the Euro Area’s Core-Periphery Divide
October 11, 2026
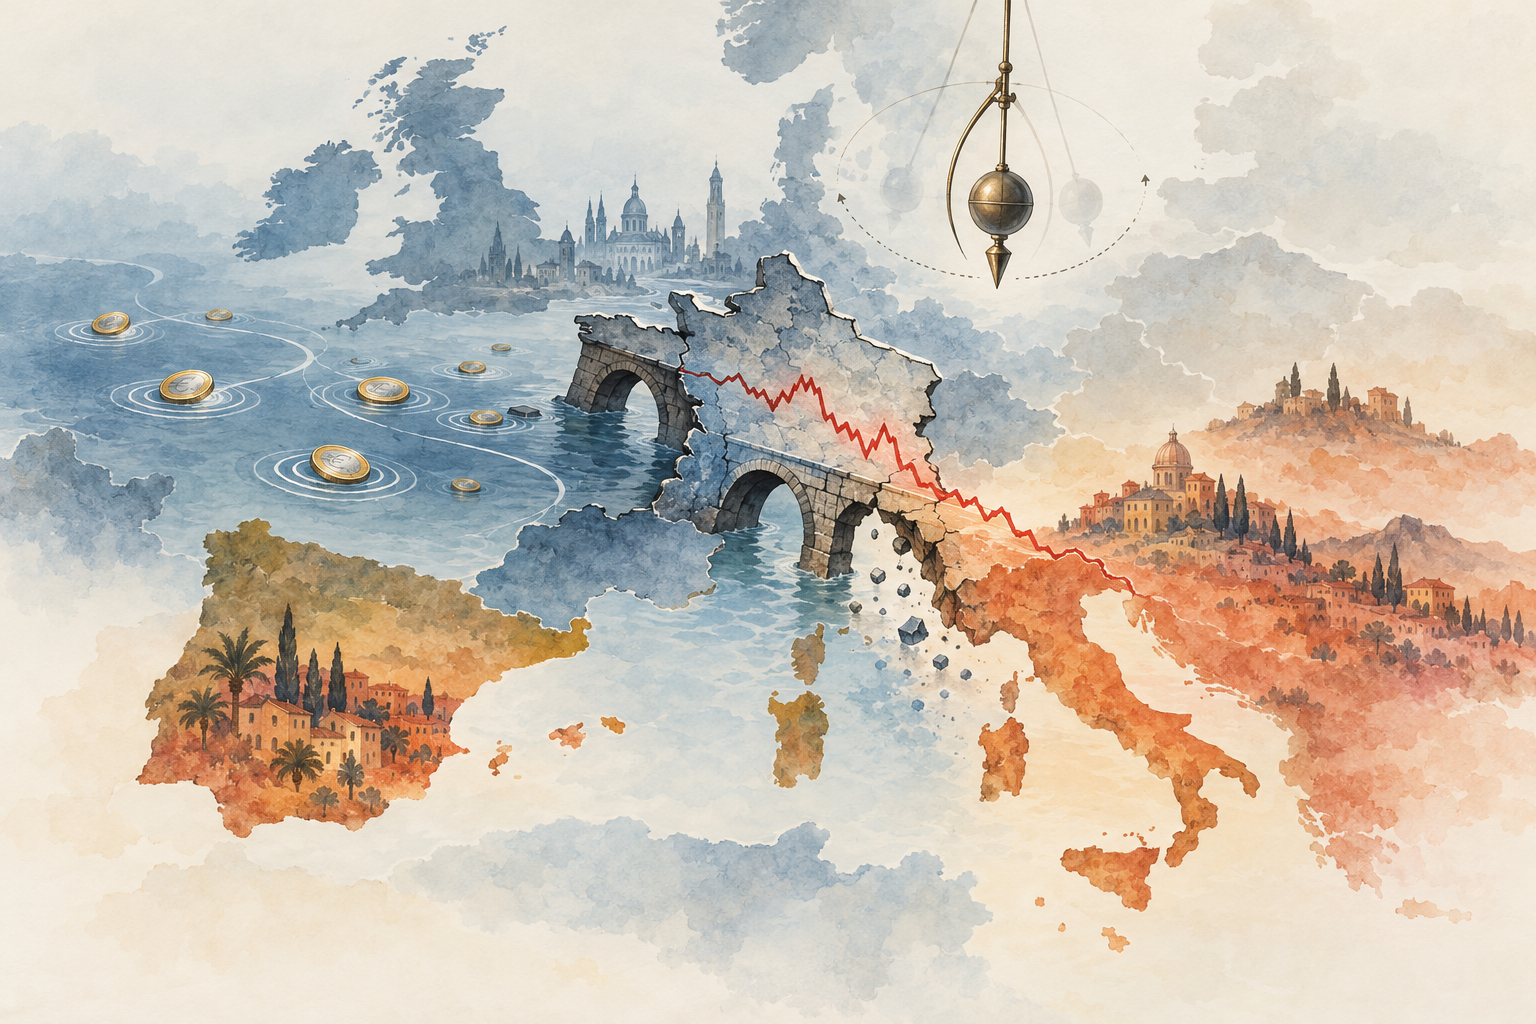
France’s 2027 budget has not stopped investors from demanding a larger premium for holding OATs, raising the question of whether Paris is still priced as a core euro-area borrower. The repricing is feeding into the euro, narrowing the traditional gap between French and Italian debt risk, and complicating the European Central Bank’s room to keep tightening.
9m
7m
UK gilt risk shifts from rates to fiscal credibility
Thirty-year gilt yields near 6% are signaling that investors are charging the UK a credibility premium ahead of the 28 October Budget. A November Bank of England hike may support sterling, but it may not be enough to cap long-end yields if fiscal plans fail to reassure markets.
7m
Big-bank earnings to test whether higher rates remain a tailwind
JPMorgan, Goldman Sachs, Citigroup and Wells Fargo report before the open on Tuesday, October 13, giving investors the first major read on whether rising Treasury yields are lifting bank income or starting to hurt loan demand, market activity and valuations.
7m
CPI, Bank Earnings to Test Wall Street’s Higher-Rate Rally
US equities enter a pivotal week near record highs, with investors betting that earnings strength can offset 10-year Treasury yields above 5%. September CPI, retail sales and major bank results will show whether that buffer is strong enough before the Federal Reserve’s October meeting.
Fast Retailing’s record year shows the consumer slowdown is sparing apparel’s strongest operators
October 9, 2026
Uniqlo owner Fast Retailing delivered a fifth straight record annual profit as North America and Europe overtook Greater China, underscoring how scale, disciplined pricing and overseas expansion are separating winners from weaker discretionary retailers.
7m
7m
TSMC’s record quarter shows AI chip demand is no longer enough
TSMC’s record third-quarter revenue confirmed that AI hardware demand remains powerful, but the market reaction showed investors have moved on to tougher questions about valuation, debt-funded infrastructure and earnings quality.
5m
China’s Fuel-Export Restart Eases the Squeeze, but Not the Energy Shock
China’s planned restart of October diesel, gasoline and jet-fuel exports should add near-term supply to a strained refined-products market. But the volumes are more likely to cap the sharpest cracks than to neutralize fuel-led inflation, bond-yield volatility or transport-sector cost pressure.
7m
Tesco Upgrade Reinforces UK Food Retail’s Defensive Case — With Christmas Still the Margin Test
Tesco’s higher profit floor, stronger free cash flow and enlarged buyback show how scale can protect earnings in a pressured consumer market. For UK equity investors, the question is whether promotions and cost inflation dilute that resilience into the festive quarter.
UK energy anxiety turns oil shock into a Bank of England problem
October 9, 2026
Record concern over energy and fuel costs in the latest ONS business survey shows the Brent rally is already feeding into company-level inflation risk. That raises the chance that firms defend margins through pricing, keeping UK services inflation and rate-hike expectations sticky.
6m
6m
PepsiCo earnings face pricing-power test after Constellation’s mixed signal
PepsiCo’s third-quarter report is set to test whether global staples companies can still protect margins with pricing and productivity as consumers resist higher shelf prices. Constellation Brands’ latest quarter suggests profits can hold up, but only with a widening gap between shipment-led sales and softer end-demand signals.
10m
BoE gilt repo reforms test trade-off between resilience and liquidity
AIMA’s warning to the Bank of England puts a live policy trade-off at the centre of sterling rates: central clearing could make gilt financing more resilient, but it may also raise funding costs and reduce liquidity when markets are under stress.
7m
Shell’s Q3 update shifts focus from crude prices to refining cash conversion
Shell’s latest third-quarter update points to a potentially material downstream boost, with indicative refining margins rising to $42 a barrel from $24 in Q2. But UK equity investors will need to separate that margin windfall and resilient trading from weaker chemicals, higher tax, emissions-certificate timing and ARC-related balance-sheet effects.
EU-China talks put European industrial margins at risk
October 8, 2026
Maros Sefcovic’s Beijing talks are a market test of whether Brussels can narrow a roughly €360 billion goods deficit with China without triggering retaliation against Europe’s exporters. Autos, machinery, chemicals and clean-tech suppliers face the sharpest equity implications because they sit on both sides of the trade equation: dependent on Chinese demand, but increasingly exposed to Chinese import competition at home.
9m
7m
Fed minutes shift markets from peak-rate debate to discount-rate stress test
Minutes from the Federal Reserve’s September meeting showed most policymakers still expected another rate increase by year-end, reinforcing pressure on long-dated bond yields, the dollar and equity valuations. The renewed tightening risk is transmitting quickly into UK gilts, European sovereign debt, stock multiples and dollar-sensitive markets.
6m
Gold’s rally is turning into a fiscal-risk trade
Gold rose on October 6 even with real Treasury yields still historically restrictive, a sign that investors are using bullion to hedge sovereign-debt credibility and liquidity risks rather than simply Fed policy. French bond stress and concern over U.S. Treasury markets are turning gold into a broader portfolio hedge against policy uncertainty.
7m
U.S. Trade Gap Shows AI Investment Boom Spilling Into Imports
The U.S. trade deficit widened 13.7% to $105.6 billion in August as imports hit a record, led by capital goods tied partly to AI infrastructure. That is a mechanical drag on Q3 GDP, but it also signals that U.S. growth outperformance is being reshaped by an investment cycle whose benefits depend on future productivity payoffs.
Clarkson Upgrade Shows Trade Disruption Is Becoming a Service-Company Earnings Story
October 7, 2026
Clarkson’s forecast for at least £135 million of 2026 underlying pretax profit points to a direct earnings read-through from geopolitical disruption, freight-rate volatility and commodity-flow dislocation. For UK small- and mid-cap investors, the update shows that an asset-light shipbroker can capture upside from shipping turmoil without owning the vessels or cargoes at the centre of it.
7m
6m
Germany’s Order Shock Tests Europe’s Narrow Industrial Rebound
German manufacturing orders plunged 10.6% in August, far worse than expected, as large transport contracts reversed. Excluding those volatile orders, the monthly decline was modest, but the three-month trend still points to weak underlying demand and a fragile eurozone factory recovery.
8m
Mann’s Wage Warning Shifts BoE Focus to Inflation Persistence
Catherine Mann’s warning that above-target UK inflation has become embedded puts the early-2027 pay round at the centre of the November Bank of England debate. For rates and sterling investors, the question is no longer only whether activity is weakening, but whether policymakers think wage settlements could lock in a higher inflation regime.
8m
Europe’s Q3 Earnings Test: Can Growth Outrun Bond Yields?
STOXX 600 third-quarter earnings are expected to rise 19.4%, but the headline depends heavily on energy. Investors now need evidence that banks, defensives and global industrials can carry profit growth if oil prices cool and higher yields pressure demand.
Eurozone PMIs Keep ECB Tightening Risk Alive as France Lifts Yields
October 5, 2026
September PMI data point to the eurozone’s strongest private-sector expansion since April 2023, complicating the bond market’s hope that fiscal stress will force the ECB into patience. For investors, better growth supports earnings but also raises the risk that the central bank tolerates tighter financial conditions for longer.
7m
5m
UK Services PMI Puts Inflation Signal Ahead of Growth
The UK’s September services PMI is set to test whether softer headline growth is enough to calm Bank of England rate risks. For sterling and gilts, the cleaner signal may be persistent services price pressure and a labour market that is cooling only slowly.
7m
Nikkei rally tests Japan’s fiscal credibility as long JGB yields hit record
Japan’s equity rally is leaning harder on a narrow assumption: Prime Minister Sanae Takaichi can deliver growth-supporting fiscal policy without convincing bond and currency markets that debt issuance and yen weakness are about to worsen. The sharp rise in the Nikkei above 70,000 and a record 30-year JGB yield show investors are rewarding stimulus hopes while simultaneously demanding proof of fiscal discipline.
8m
OPEC+ pause turns $100 oil into a test for bond markets
Core OPEC+ producers’ decision to keep November output targets steady leaves the oil market short of an immediate supply cushion just as investors look for evidence that inflation and yields can stabilise. For macro investors, the risk is that energy prices keep bleeding into European costs, inflation expectations and rate pricing ahead of services PMI and U.S. ISM data.
Nvidia’s $235 Billion Buyback Puts AI Cash Flow to the Test
October 4, 2026
Nvidia’s record buyback authorization is less a retreat from AI investment than a new yardstick for judging whether the company can convert artificial-intelligence demand into durable free cash flow. For equity investors, the question is no longer only how fast Nvidia can grow, but how much cash it can return while still funding the ecosystem that protects its lead.
9m
5m
Golden Week’s travel boom may not deliver a profit boom
China’s National Day Golden Week is delivering heavy transport and tourism volumes, but the investor question is whether mobility is converting into higher-margin spending. Early signals point to a split between traffic and monetisation, with Hong Kong’s sharp equity selloff underscoring concern across China-exposed consumer cyclicals.
8m
BAE’s Robin Radar Interest Tests Strategic Appetite for Counter-Drone Multiples
A possible €2 billion sale of Dutch drone-detection specialist Robin Radar would test whether defence primes can outbid private equity for scarce counter-drone infrastructure. The politics of European security screening may matter as much as headline valuation.
6m
Axis’s Possible PTSB Counterbid Tests European Bank Takeover Premiums
Axis Capital’s possible €3.20-a-share cash offer for Permanent TSB would top BAWAG’s agreed €2.97 scheme and give minority shareholders a late valuation benchmark. But the proposal remains conditional on financing, due diligence and Irish takeover-rule mechanics.
BT’s TalkTalk rescue dilemma tests UK broadband competition limits
October 4, 2026
TalkTalk’s worsening finances could make a BT approach look like a rescue rather than a market-share grab. But any deal would still force ministers, Ofcom and competition authorities to weigh customer continuity against renewed concentration in UK broadband.
6m
6m
Wetherspoon rally tests whether sales momentum can outrun pub cost inflation
J D Wetherspoon’s revenue rose to £2.24bn and current trading accelerated, but adjusted pre-tax profit fell 28% as wage, repair, energy and rates costs absorbed the benefit of stronger footfall. The share-price relief looks justified only if recent like-for-like sales strength proves durable beyond exceptional summer weather.
8m
Tesla and Rivian Delivery Beats Point to Firmer EV Demand, but Margins Remain the Test
Tesla’s stronger-than-expected third-quarter deliveries and Rivian’s record quarter suggest EV demand is improving as fuel costs, model launches and European recovery support volumes. For investors, the next question is whether that recovery is being bought with discounts that dilute margins.
8m
Nuveen-Schroders Deal Makes Scale the New Survival Test in Asset Management
Nuveen’s completed acquisition of Schroders creates a $2.6 trillion investment manager and removes one of the UK market’s best-known listed fund groups. The transaction underscores how fee pressure, distribution power and private-markets capability are narrowing the strategic room for mid-sized European active managers.
Nike’s China Slump Resets the Global Brand Turnaround Trade
October 3, 2026
Nike’s latest results show that a stronger U.S. business is not enough to neutralize sharp weakness in China and EMEA. For global consumer discretionary investors, the read-across is that turnarounds deserve a steeper discount when China is no longer a dependable profit stabiliser.
6m
7m
UK mortgage resets move to the center of the bond selloff
The global bond rout is increasingly transmitting through household cash flow, not just gilt-market volatility, as UK fixed-rate borrowers refinance into mortgage rates around 5.5% to 6%. The pressure is large enough to matter for housing turnover, consumer demand and domestic-facing UK equities.
8m
IG’s Rout Puts Retail Trading Revenue Assumptions Under Pressure
IG Group’s more than 20% share-price fall looks partly company-specific, tied to weaker OTC revenue retention after changes to its market-making model. But the read-across to Plus500 and CMC Markets shows investors are questioning whether retail trading platforms can still convert macro volatility into dependable earnings growth.
5m
Small-cap results put balance sheets and refinancing in focus
UK small- and mid-cap investors face a results-heavy week in which funding costs, consumer demand and refinancing commentary may matter more than headline earnings. Updates from Tullow Oil, Redcentric, Christie Group, Likewise Group, US Solar Fund, AG Barr, Card Factory and Close Brothers arrive against a backdrop of subdued growth, volatile energy prices and tighter fiscal conditions.
UK Borrowing Overshoot Puts Gilt Market at Centre of Budget Test
September 28, 2026
UK public sector borrowing reached £18.3 billion in August, £3.5 billion above the OBR forecast, leaving investors focused on forecast slippage rather than the fact that year-to-date borrowing is still below last year’s level. With debt just under £3 trillion and the Budget set for 28 October, higher debt-service costs are narrowing Chancellor John Healey’s room for manoeuvre.
7m
3m
Sterling’s $1.32 Slide Puts UK Rates Pricing on Trial
The pound is hovering near three-month lows as oil-driven inflation risks lift the dollar and revive Fed hike bets. The bigger vulnerability for sterling is whether UK data can validate the amount of Bank of England tightening still priced into rates markets.
6m
China’s Industrial Profit Recovery Narrows as Electronics Drives the Cycle
China’s industrial profit growth slowed sharply in August, exposing a recovery increasingly dependent on electronics manufacturing and exports. For global equity investors, the split between high-tech strength and weak consumer-linked demand raises risks for miners, luxury stocks and European exporters tied to China’s domestic cycle.
7m
Brent’s Hormuz shock puts diesel pass-through at the centre of UK equity risk
Brent’s move above $106 after Washington rejected Iran’s latest Strait of Hormuz proposal is widening from an oil-price story into a margin and rates story. For UK and European markets, the pressure points are airlines, logistics, retailers and long-duration equities exposed to higher freight costs and bond yields.
Nvidia’s China Risk Shifts From Licensing Delays to Platform Displacement
September 27, 2026
Alibaba’s Zhenwu V900 chip, 20GW data-center target and multi-trillion-parameter Qwen roadmap suggest China’s AI buyers are not merely waiting for Nvidia export relief. The bigger risk for NVDA investors is that export controls are accelerating durable local alternatives in cloud and sovereign AI workloads.
7m
6m
Payrolls and Eurozone Inflation Test a Stretched Bond Market
With Treasury and gilt yields already near multi-year highs, the next U.S. labour and inflation releases could determine whether the rates sell-off pauses or starts to bite harder into equity valuations. For global macro investors, the key question is whether incoming data validate markets’ renewed central-bank tightening bets.
5m
Genel’s $436m Capricorn bid turns small-cap E&P M&A into a cash contest
Genel Energy’s raised cash offer for Capricorn Energy has shifted the takeover battle from an opportunistic bid for a discounted producer into a competitive auction for listed production, reserves and balance-sheet value. The 10% premium to DNO’s rival proposal suggests buyers are paying up for near-term barrels, Egypt exposure and oil-linked cash flows rather than waiting for distressed sellers.
7m
BP’s Devon walk-away shows shale discipline still matters above $100 oil
BP’s reported look at Devon Energy’s Eagle Ford assets shows how high crude prices are reopening shale M&A discussions, but its reported decision to walk away suggests investors still have leverage over capital allocation. For BP, a South Texas deal would need to be priced as a cash-return accelerator, not a production-growth trophy.
UK autos face EU price for softer line on Chinese EVs
September 27, 2026
Brussels’ push for Britain to raise tariffs on Chinese cars turns the UK’s post-Brexit trade flexibility into a potential liability for manufacturers seeking access to EU industrial-support schemes. The equity impact is most direct for UK-listed suppliers tied to regional supply chains, while exporters face a broader rules-of-origin and procurement risk.
8m
6m
Corporate Debt Wall Turns Rate Shock Into an Earnings Risk
Roughly $4.3 trillion of U.S.-market non-financial corporate bonds mature from 2027 through 2031, just as Treasury yields sit near post-2007 highs. The greatest pressure is concentrated in lower-rated high-yield and CCC borrowers, while AI-driven technology issuance could crowd an already heavy refinancing calendar.
7m
Weak Yen Becomes U.S.-Japan Flashpoint, Raising Intervention Risk
Japan’s disclosure that President Trump raised yen weakness with Prime Minister Sanae Takaichi shifts USD/JPY from a domestic BOJ-inflation trade into a bilateral currency and trade issue. For macro investors, that raises the probability of coordinated verbal intervention—and increases the tail risk of another official yen-buying operation.
5m
Eurozone business lending slows as higher yields raise financing hurdle
ECB data showed corporate loan growth slowed in August while household lending held steady, raising the risk that eurozone credit momentum is peaking just as bond yields and rate expectations move higher. The signal is not yet a credit crunch, but it narrows the upside from firmer activity data and complicates the setup for bank stocks.
AI Capex Turns Into a Rates Problem for Equities
September 26, 2026
August’s upside surprise in US core capital-goods orders shows AI infrastructure spending is still strong enough to support growth. That strength is also helping keep Treasury yields and rate expectations elevated, complicating the valuation case for equities.
6m
8m
French OATs Become Europe’s Fiscal Credibility Test as ECB Backstop Assumptions Recede
French bond stress is shifting from a broad rates repricing into a country-specific test of fiscal credibility, with the 2027 budget and presidential election now central to whether investors treat OATs as the euro area’s main sovereign-risk gauge. Bank of France Governor Emmanuel Moulin’s warning that Paris cannot rely on the ECB underscores a harder market question: what domestic adjustment is required before any crisis backstop is politically or institutionally credible?
6m
H&M’s profit beat needs stronger sales to hold up
H&M beat third-quarter profit expectations, but the earnings surprise was flattered by temporary tariff and import effects while sales growth stayed weak. For retail investors, the key question is whether cost discipline can bridge the gap until top-line momentum improves.
5m
Germany’s Ifo Beat Supports Europe’s Cyclicals, but Upside Still Looks Capped
Germany’s September Ifo surprise and upgraded 2026 growth outlook strengthen the case that Europe’s cyclical earnings trough is passing. But high fuel costs and elevated bond yields leave the recovery too narrow to fully underwrite bullish earnings expectations.
Raspberry Pi rally puts hardware margins in focus
September 25, 2026
Raspberry Pi shares surged after first-half revenue and pretax profit rose sharply, but the quality of the beat is being tested by memory-cost inflation and fading inventory benefits. For UK small-cap investors, the question is whether public markets will reward profitable hardware growth when component risk is rising.
6m
7m
BoE hawks shift energy shock into rate-hike debate
Money markets are no longer debating only how long Bank of England cuts will be delayed. After Deputy Governors Clare Lombardelli and Sarah Breeden both warned that persistent energy costs could require tighter policy, traders are pricing at least one hike as a genuine, though still conditional, MPC pivot.
6m
UK Confidence Beat Complicates the Bank of England’s Demand-Slowdown Case
GfK’s UK consumer-confidence gauge rose to -13 in September, beating expectations and reaching its strongest level since August 2024. But weak retail orders, rising fuel costs and renewed energy inflation risks mean the improvement may be a fragile support for discretionary spending rather than a clean signal of stronger demand.
7m
Renishaw’s Record Year Sharpens the UK AI Equipment Re-rating Test
Renishaw’s FY2026 beat is more than a single-stock recovery story: it is one of the cleaner UK-listed signals that AI-linked semiconductor equipment demand is feeding through to precision manufacturing suppliers. The question for investors is whether record revenue and expanding margins mark a cyclical upswing or the start of a more durable valuation reset for UK advanced manufacturing exposure.
US-China truce extension steadies markets, but January deadline caps equity upside
September 24, 2026
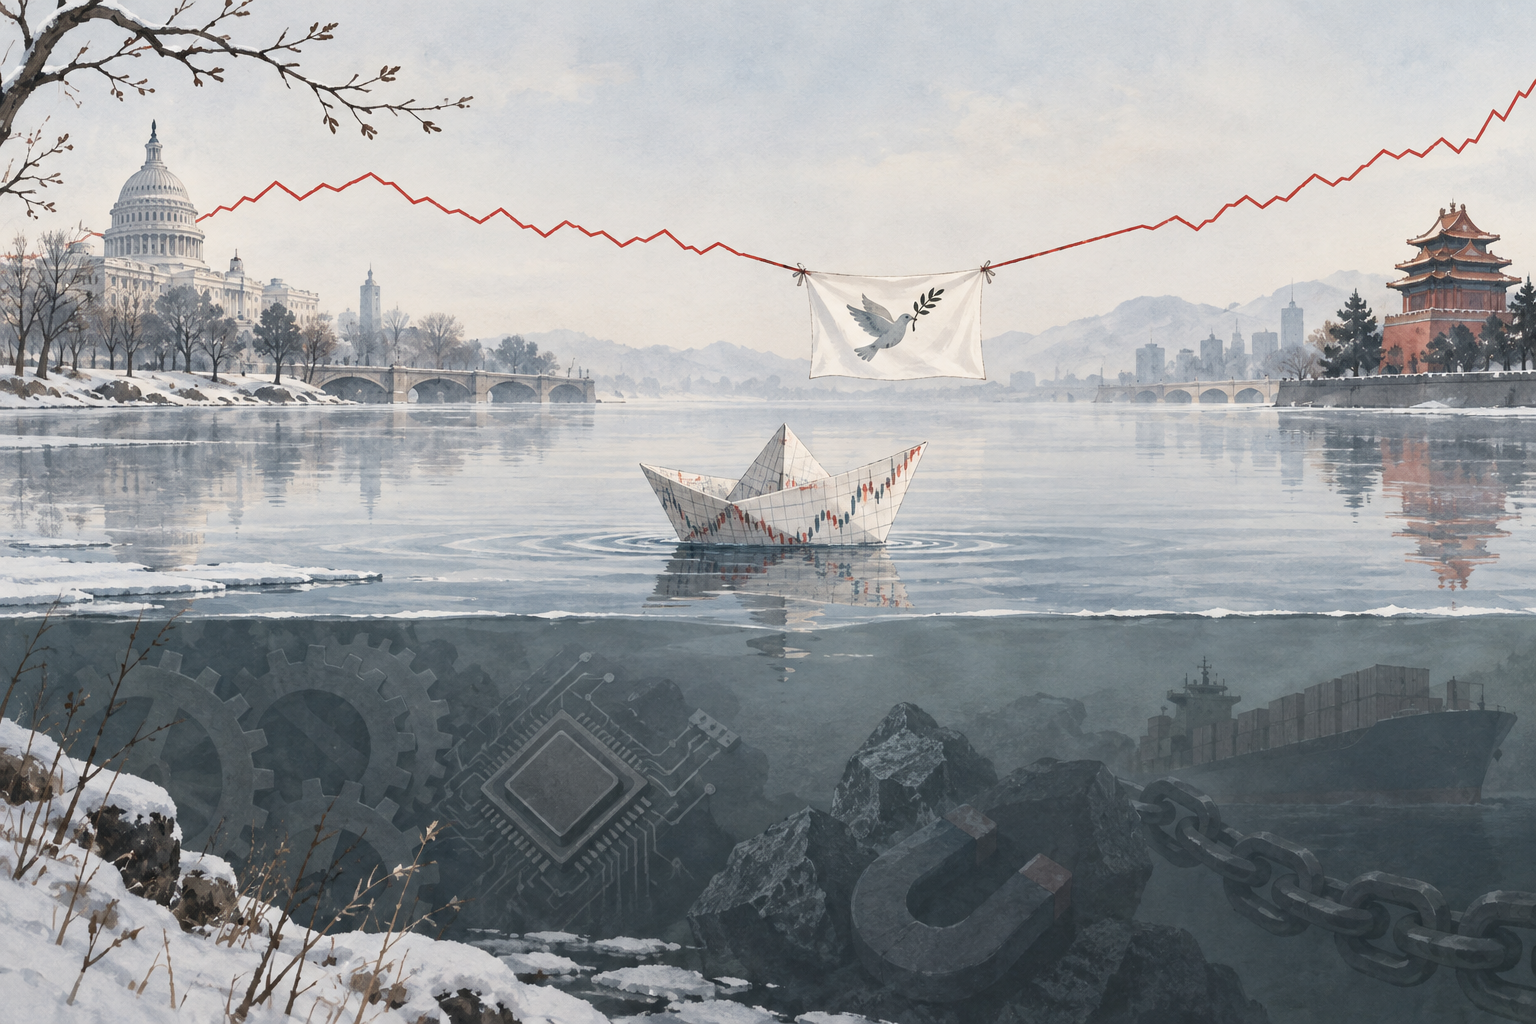
Washington and Beijing’s agreement to extend the Busan trade truce to Jan. 10 suppresses near-term tariff and supply-chain volatility, but investors have not treated it as a growth upgrade. The read-through is most supportive for exposed cyclicals and luxury in the short run, while rare-earth, technology-control and enforcement risks remain unresolved.
7m
5m
Strong US Growth Is Becoming the Market’s Problem
A five-year high in the US flash composite PMI has shifted the risk narrative from recession to resilience. Stronger demand is hardening the case for tighter financial conditions, pressuring global equity valuations, sterling assets and rate-sensitive sectors.
7m
Eurozone PMI Surprise Tests Case for Earnings Rotation
The eurozone’s September PMI rebound strengthens the case for a broader European equity rotation, but the hurdle is now margins rather than activity. Investors need proof that stronger orders can outweigh higher energy-linked input costs and a potentially more hawkish ECB.
You've reached the end